XPENG's Q3 cash pile and the valuation question, read through deliveries
A Chinese analyst argues XPENG's RMB 45.4bn cash pile leaves only RMB 17.5bn of enterprise value, and weighs deliveries, revenue mix and future growth against that.
A Chinese automotive analyst, DannyData小丹尼, published a valuation note on Weibo on 18 November 2026 arguing that XPENG's market capitalisation understates the business once its cash is stripped out. The post is an outside analyst's opinion built on XPENG's Q3 2026 financials, not a company statement, but it pulls together the quarter's delivery, revenue and margin numbers in one place and is worth reading on that basis.
The arithmetic at the centre of it: XPENG's market value was RMB 62.9 billion on 18 November, against RMB 45.4 billion in cash and equivalents reported in the latest Q3 results. Subtract one from the other and the analyst arrives at roughly RMB 17.5 billion for the operating business. That framing is his, and it treats cash as fully attributable to equity holders, which is a simplification. The underlying figures are the company's.
Deliveries: a record quarter, but a modest one
XPENG delivered 118,390 vehicles in Q3 2026, up 2.1% year on year and 14.6% quarter on quarter. It is a quarterly record, but as the analyst notes, it is close to the levels reached in the third and fourth quarters of the previous year — roughly 40,000 a month.
The more interesting number is the guidance. Management guided Q4 to 169,000–174,000 deliveries, which implies about 57,000 a month if met. October came in at 50,200 units, a monthly record, and management expects November to exceed 60,000 for the first time. The analyst treats that guidance, rather than the Q3 result, as the year's real highlight.
Average selling price tells the other half of the story. Automotive revenue of RMB 21.63 billion across 118,390 units works out to about RMB 183,000 per car. In October, 16,563 of XPENG's 36,911 deliveries were MONA L03 and 7,160 were MONA M03 — together about 64% of the month — and that was before MONA L05 had started delivering.
Revenue mix and margins
Total Q3 revenue was RMB 24.28 billion, of which automotive sales were RMB 21.63 billion, up 19.8% year on year and 23% quarter on quarter. The roughly RMB 2.65 billion gap is mainly technical service revenue from Volkswagen, about 10.9% of the total.
Automotive revenue growing faster than service revenue is, in the analyst's reading, a healthier mix: less of the result depends on the Volkswagen arrangement. Gross margin on vehicles was 13.1%, while the service segment carried 67.1%. Because service is the high-margin line, the blended gross margin fell as its share of revenue dropped — the analyst's point is that the prior four quarters' 20%-plus blended margins leaned on that service income rather than on selling cars.
The net loss for the quarter narrowed to RMB 870 million. Cash and equivalents rose by close to RMB 5 billion over the quarter, which the earnings call attributed in part to operating cash flow exceeding RMB 2 billion. R&D spending edged down slightly, and the analyst notes the expense ratio reached a new low for recent quarters, having sat around 25% for the past two years.
What this means for owners
Little here changes anything about the car in your driveway, but two things are worth tracking. First, the Q4 guidance of 169,000–174,000 deliveries is a company commitment; if November does pass 60,000, that is the first hard evidence the ramp is real rather than seasonal. Second, the growing weight of MONA models in the mix is the clearest signal of where XPENG's volume — and therefore its software fleet — is heading. The analyst's remaining growth arguments (Robotaxi, robotics, flying cars and overseas expansion) are covered elsewhere on this blog and are not detailed in this post.
Sources
- 小鹏被低估了吗? — Weibo, DannyData小丹尼, 18 November 2026
Photos from the source posts
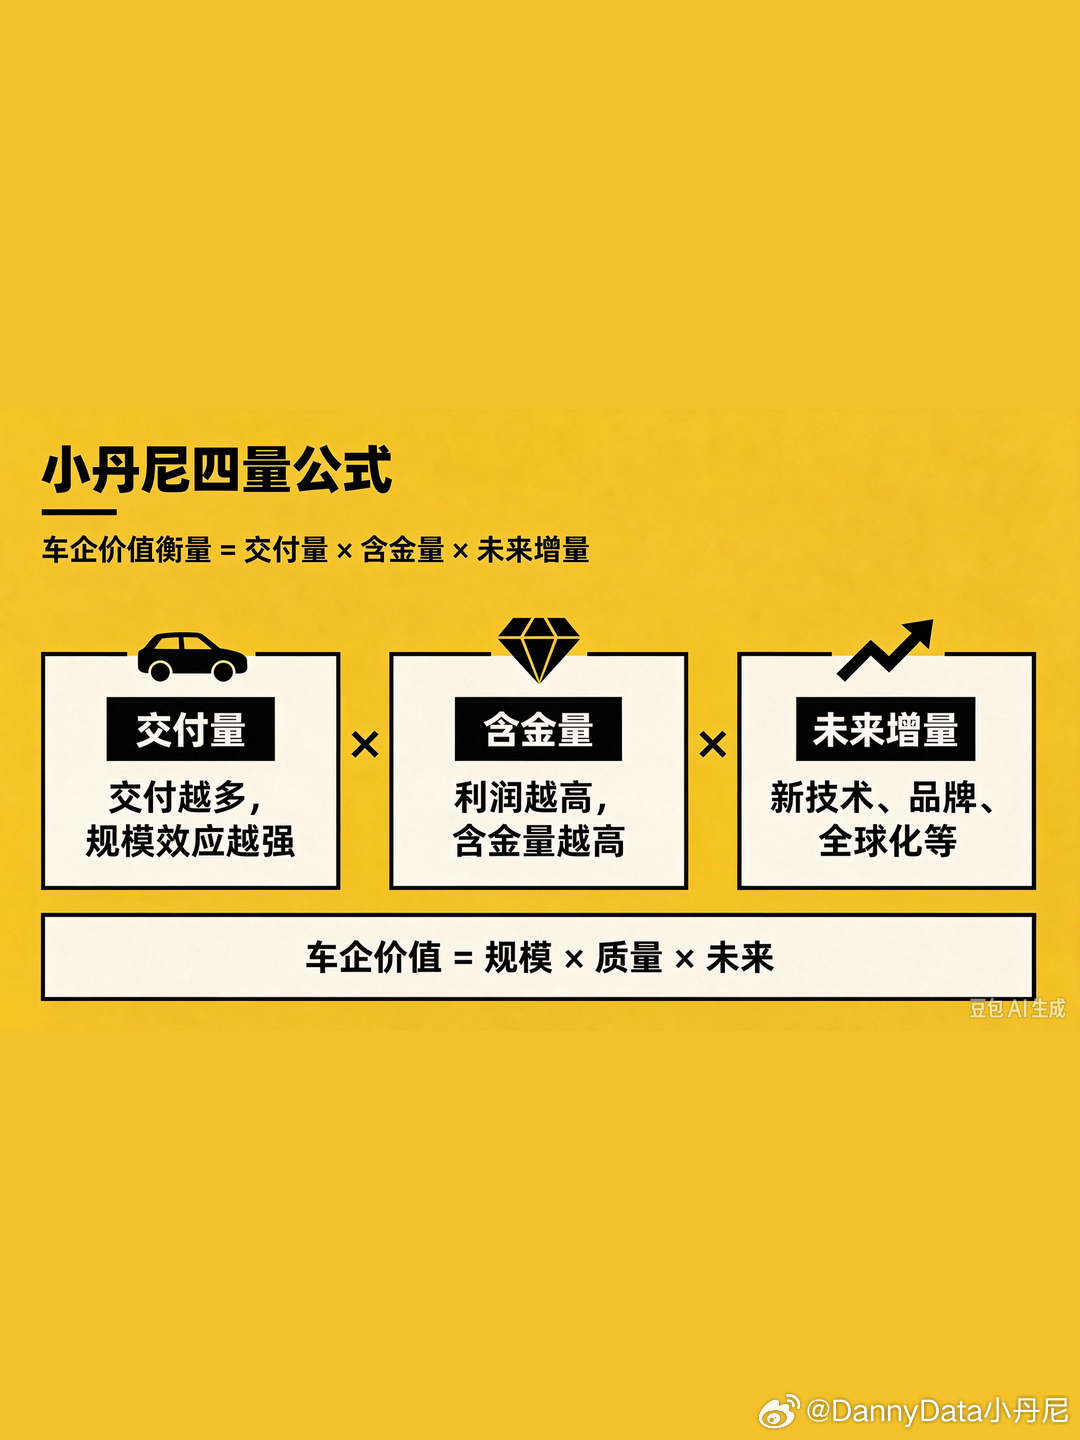 Photo: DannyData小丹尼 on Weibo — original post
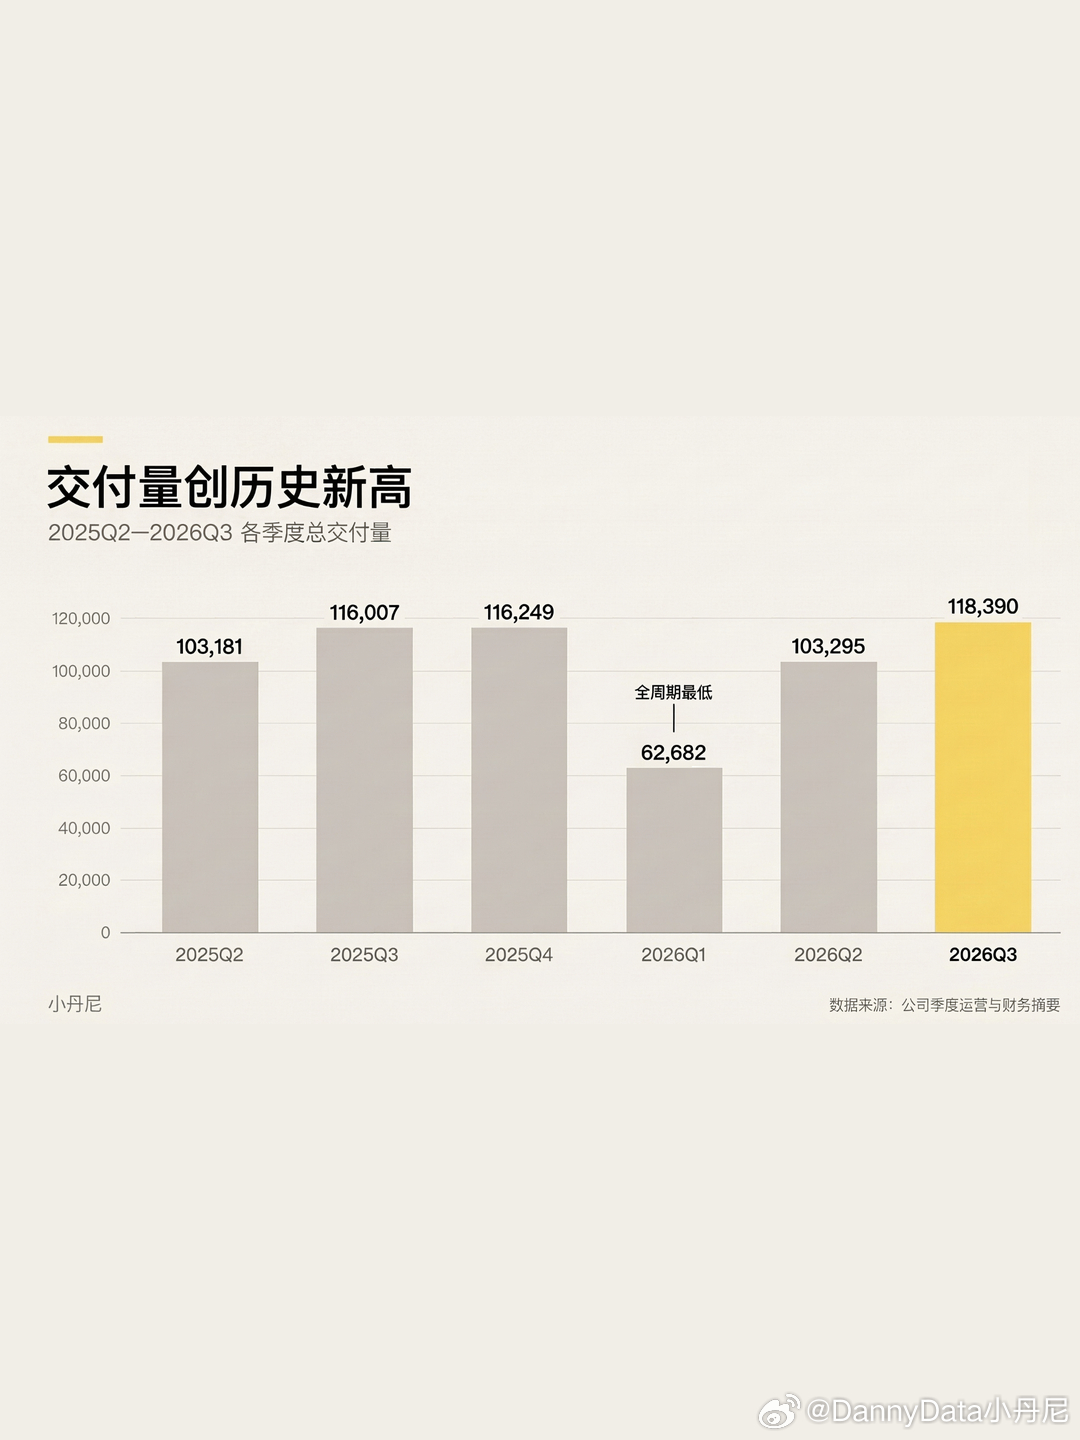 Photo: DannyData小丹尼 on Weibo — original post
Enjoyed this? Get the next one direct.
New articles, or a daily / weekly digest — delivered to your inbox.