XPENG posts record Q3 2026 results and guides Q4 deliveries up 45%
XPENG's Q3 2026: 118,390 deliveries, RMB 24.28bn revenue, 18.9% gross margin, RMB 45.41bn cash. Q4 guidance of 169,000-174,000 vehicles would be another record.
XPENG published its third-quarter 2026 results on Weibo, reporting record quarterly deliveries and revenue, and issued fourth-quarter guidance that implies a further step up in volume. The numbers matter to owners less for the headline than for what they say about the company's ability to keep funding software development and new models.
The Q3 numbers
All figures below are from XPENG's own post.
- Deliveries: 118,390 vehicles, up 2.1% year on year and up 14.6% on Q2 2026. The company describes this as a quarterly delivery record.
- Revenue: RMB 24.28 billion, up 19.1% year on year and up 23.0% on Q2 2026. Also described as a quarterly record.
- Margins: 18.9% gross margin overall, with automotive gross margin at 13.1%.
- Cash: RMB 45.41 billion (USD 6.77 billion) in cash and cash equivalents, restricted cash, short-term investments and time deposits as of 30 September 2026, a net increase of about RMB 4.93 billion versus 30 June 2026.
One detail worth noting: deliveries grew only 2.1% year on year while revenue grew 19.1%. XPENG does not explain the gap in the post, so the mix shift behind it is not something we can attribute from this source alone.
Q4 guidance
XPENG's guidance for the current quarter, again as stated in the post:
- Deliveries: 169,000 to 174,000 vehicles, up 45.38% to 49.68% year on year and up 42.75% to 46.97% on Q3.
- Revenue: RMB 30.40 billion to 31.80 billion, up 36.61% to 42.90% year on year and up 25.23% to 30.99% on Q3.
If met, that would be a substantial jump from the Q3 record. The midpoint of the delivery range is roughly 43% above Q3, which is a steep sequential ramp to commit to publicly. XPENG does not break the guidance down by model or market in this post, so there is no basis here for saying which vehicles or regions are expected to carry it.
What this means for owners
This is a financial update, not a product or software announcement, so there is nothing in it that changes your car today. A few practical readings:
- Software funding. The cash position and the margin figures are the context in which OTA programmes get funded. XPENG's post does not tie the results to any specific software roadmap, so treat any link between these numbers and a future OTA as inference, not company statement.
- No Australian detail. The post gives group-level figures only. It does not break out deliveries, revenue or guidance by country, so it says nothing specific about Australia, right-hand-drive allocation or local timing.
- Guidance is guidance. The Q4 range is a company forecast, not a result. XPENG has published it as a target; whether it lands is something the Q4 report will settle.
We have not verified these figures against XPENG's formal financial filings, and this article is based solely on the company's Weibo post. Owners wanting the full statements, including segment breakdowns and any commentary on model mix, should refer to XPENG's investor relations disclosures.
Sources
- 小鹏汽车 on Weibo — Q3 2026 results and Q4 guidance, Weibo, 小鹏汽车 (XPENG official account), 16 November 2026.
Photos from the source posts
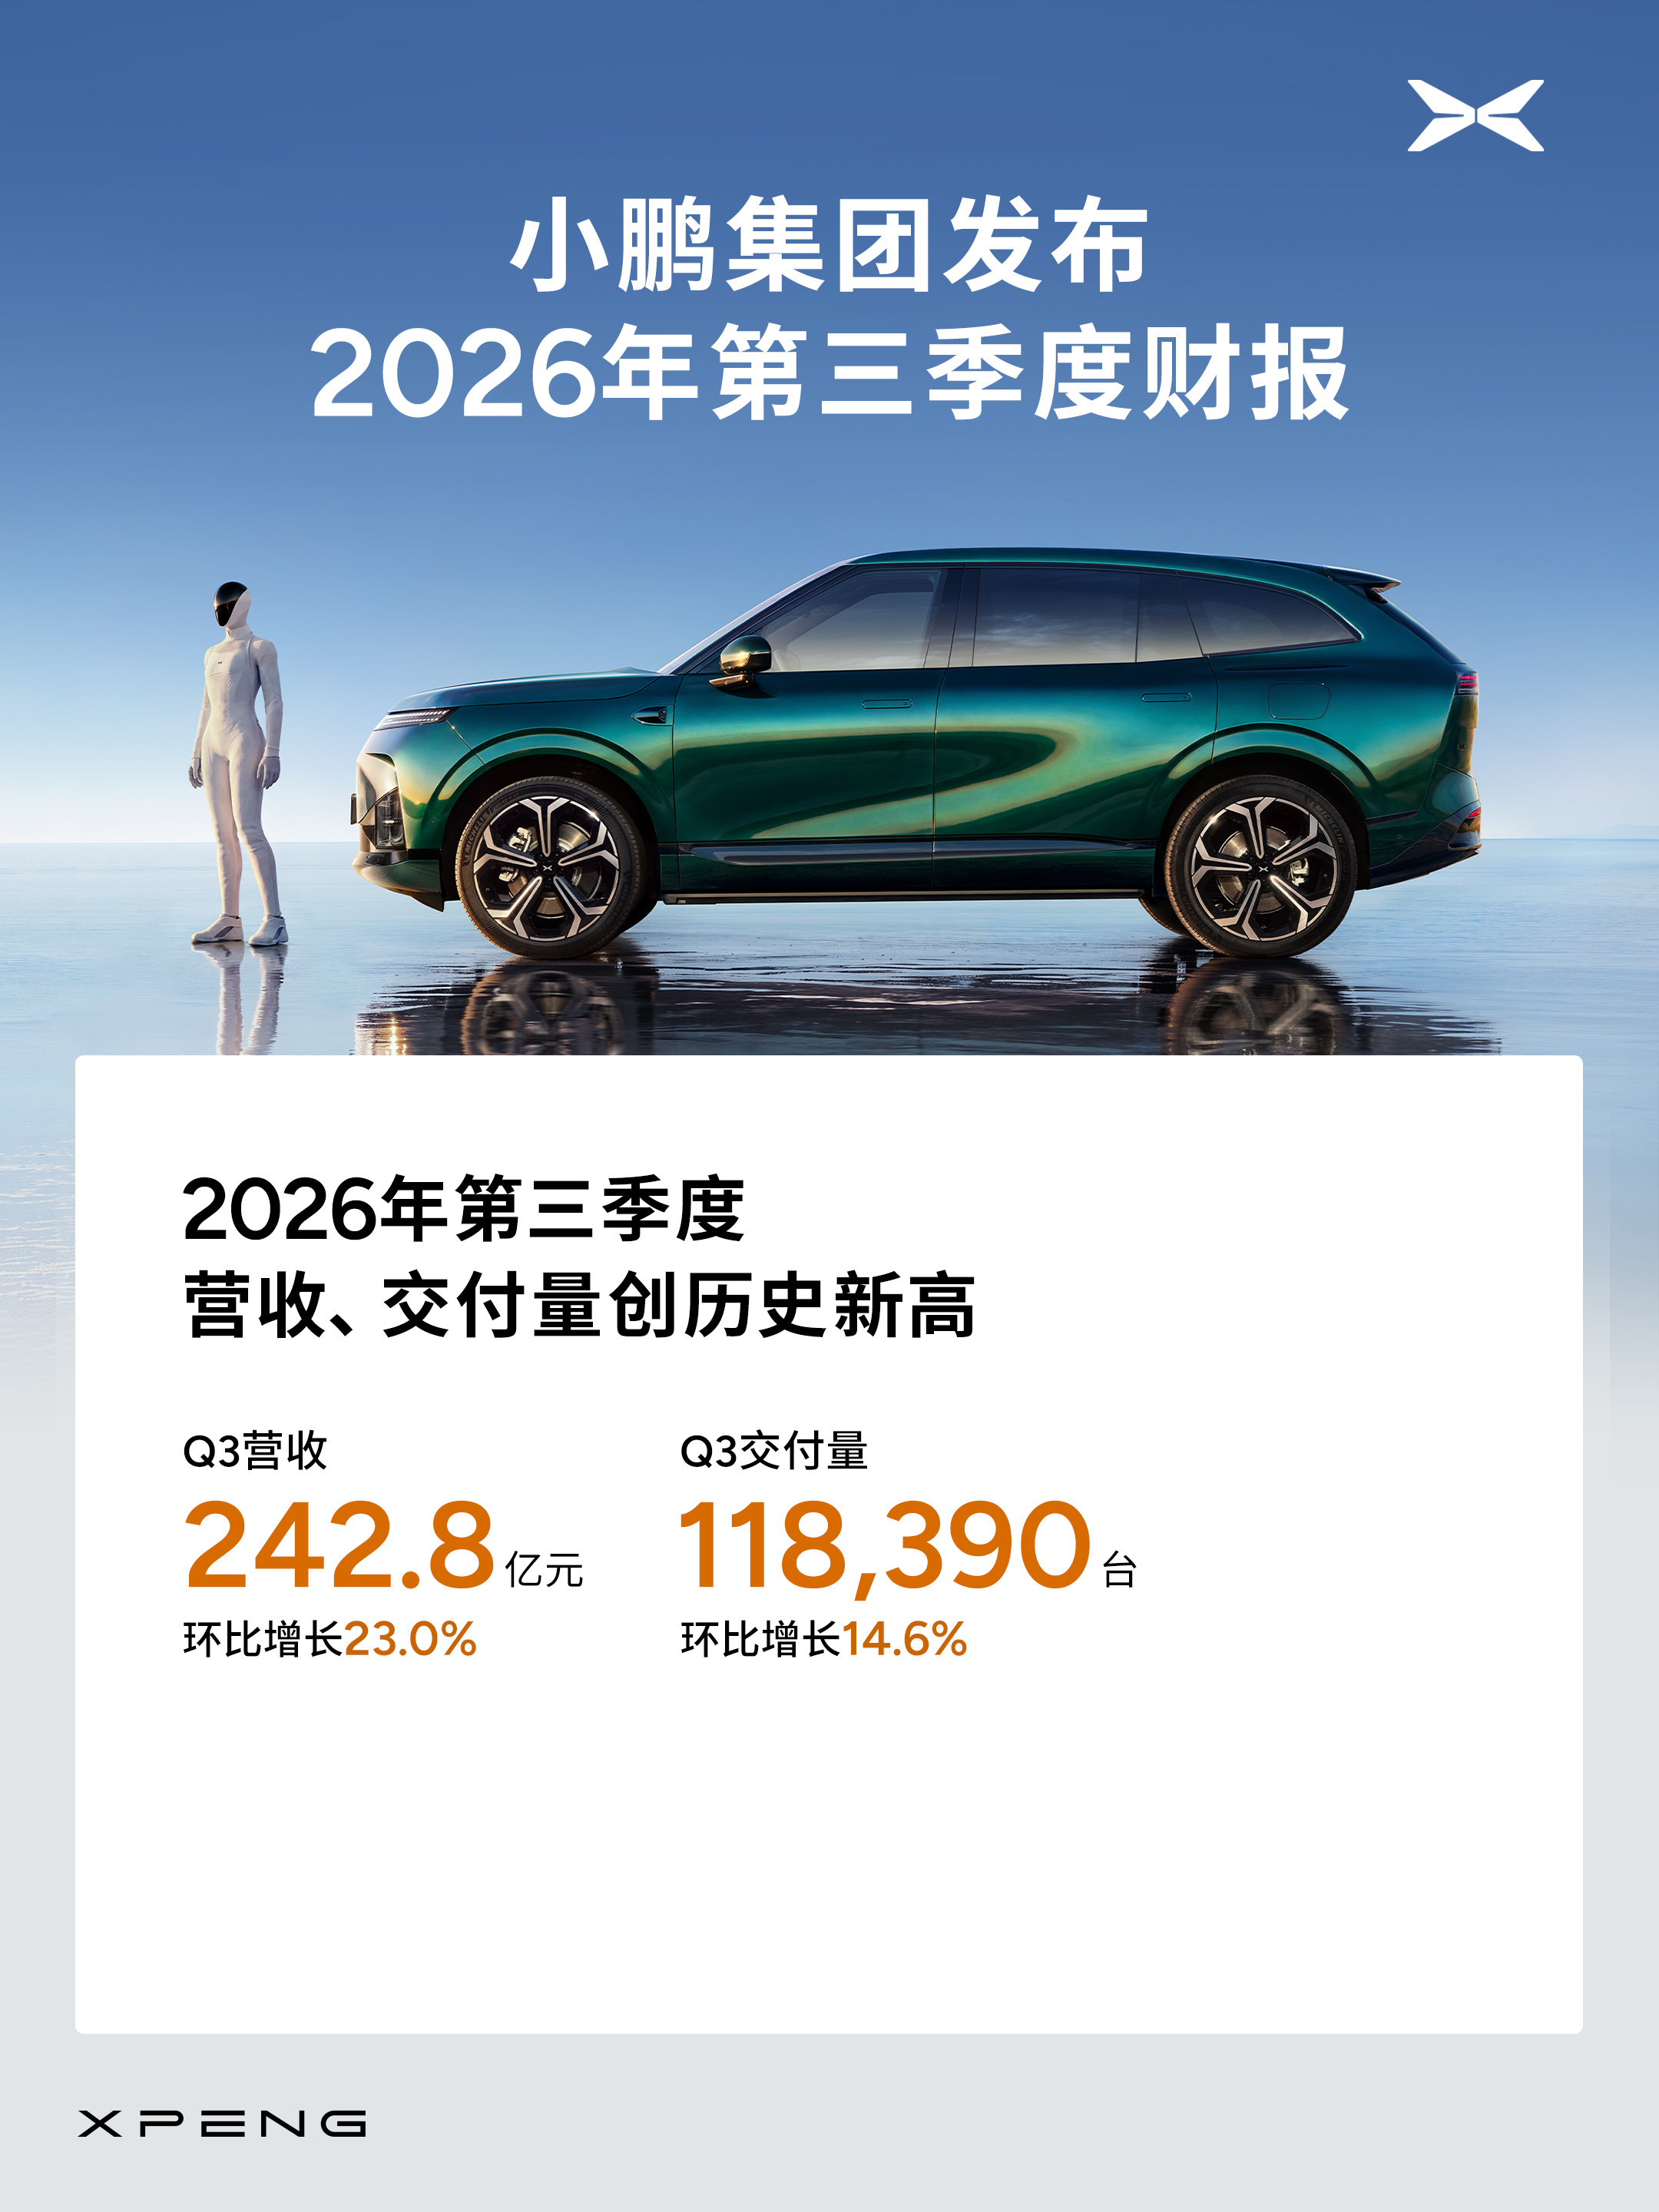 Photo: 小鹏汽车 on Weibo — original post
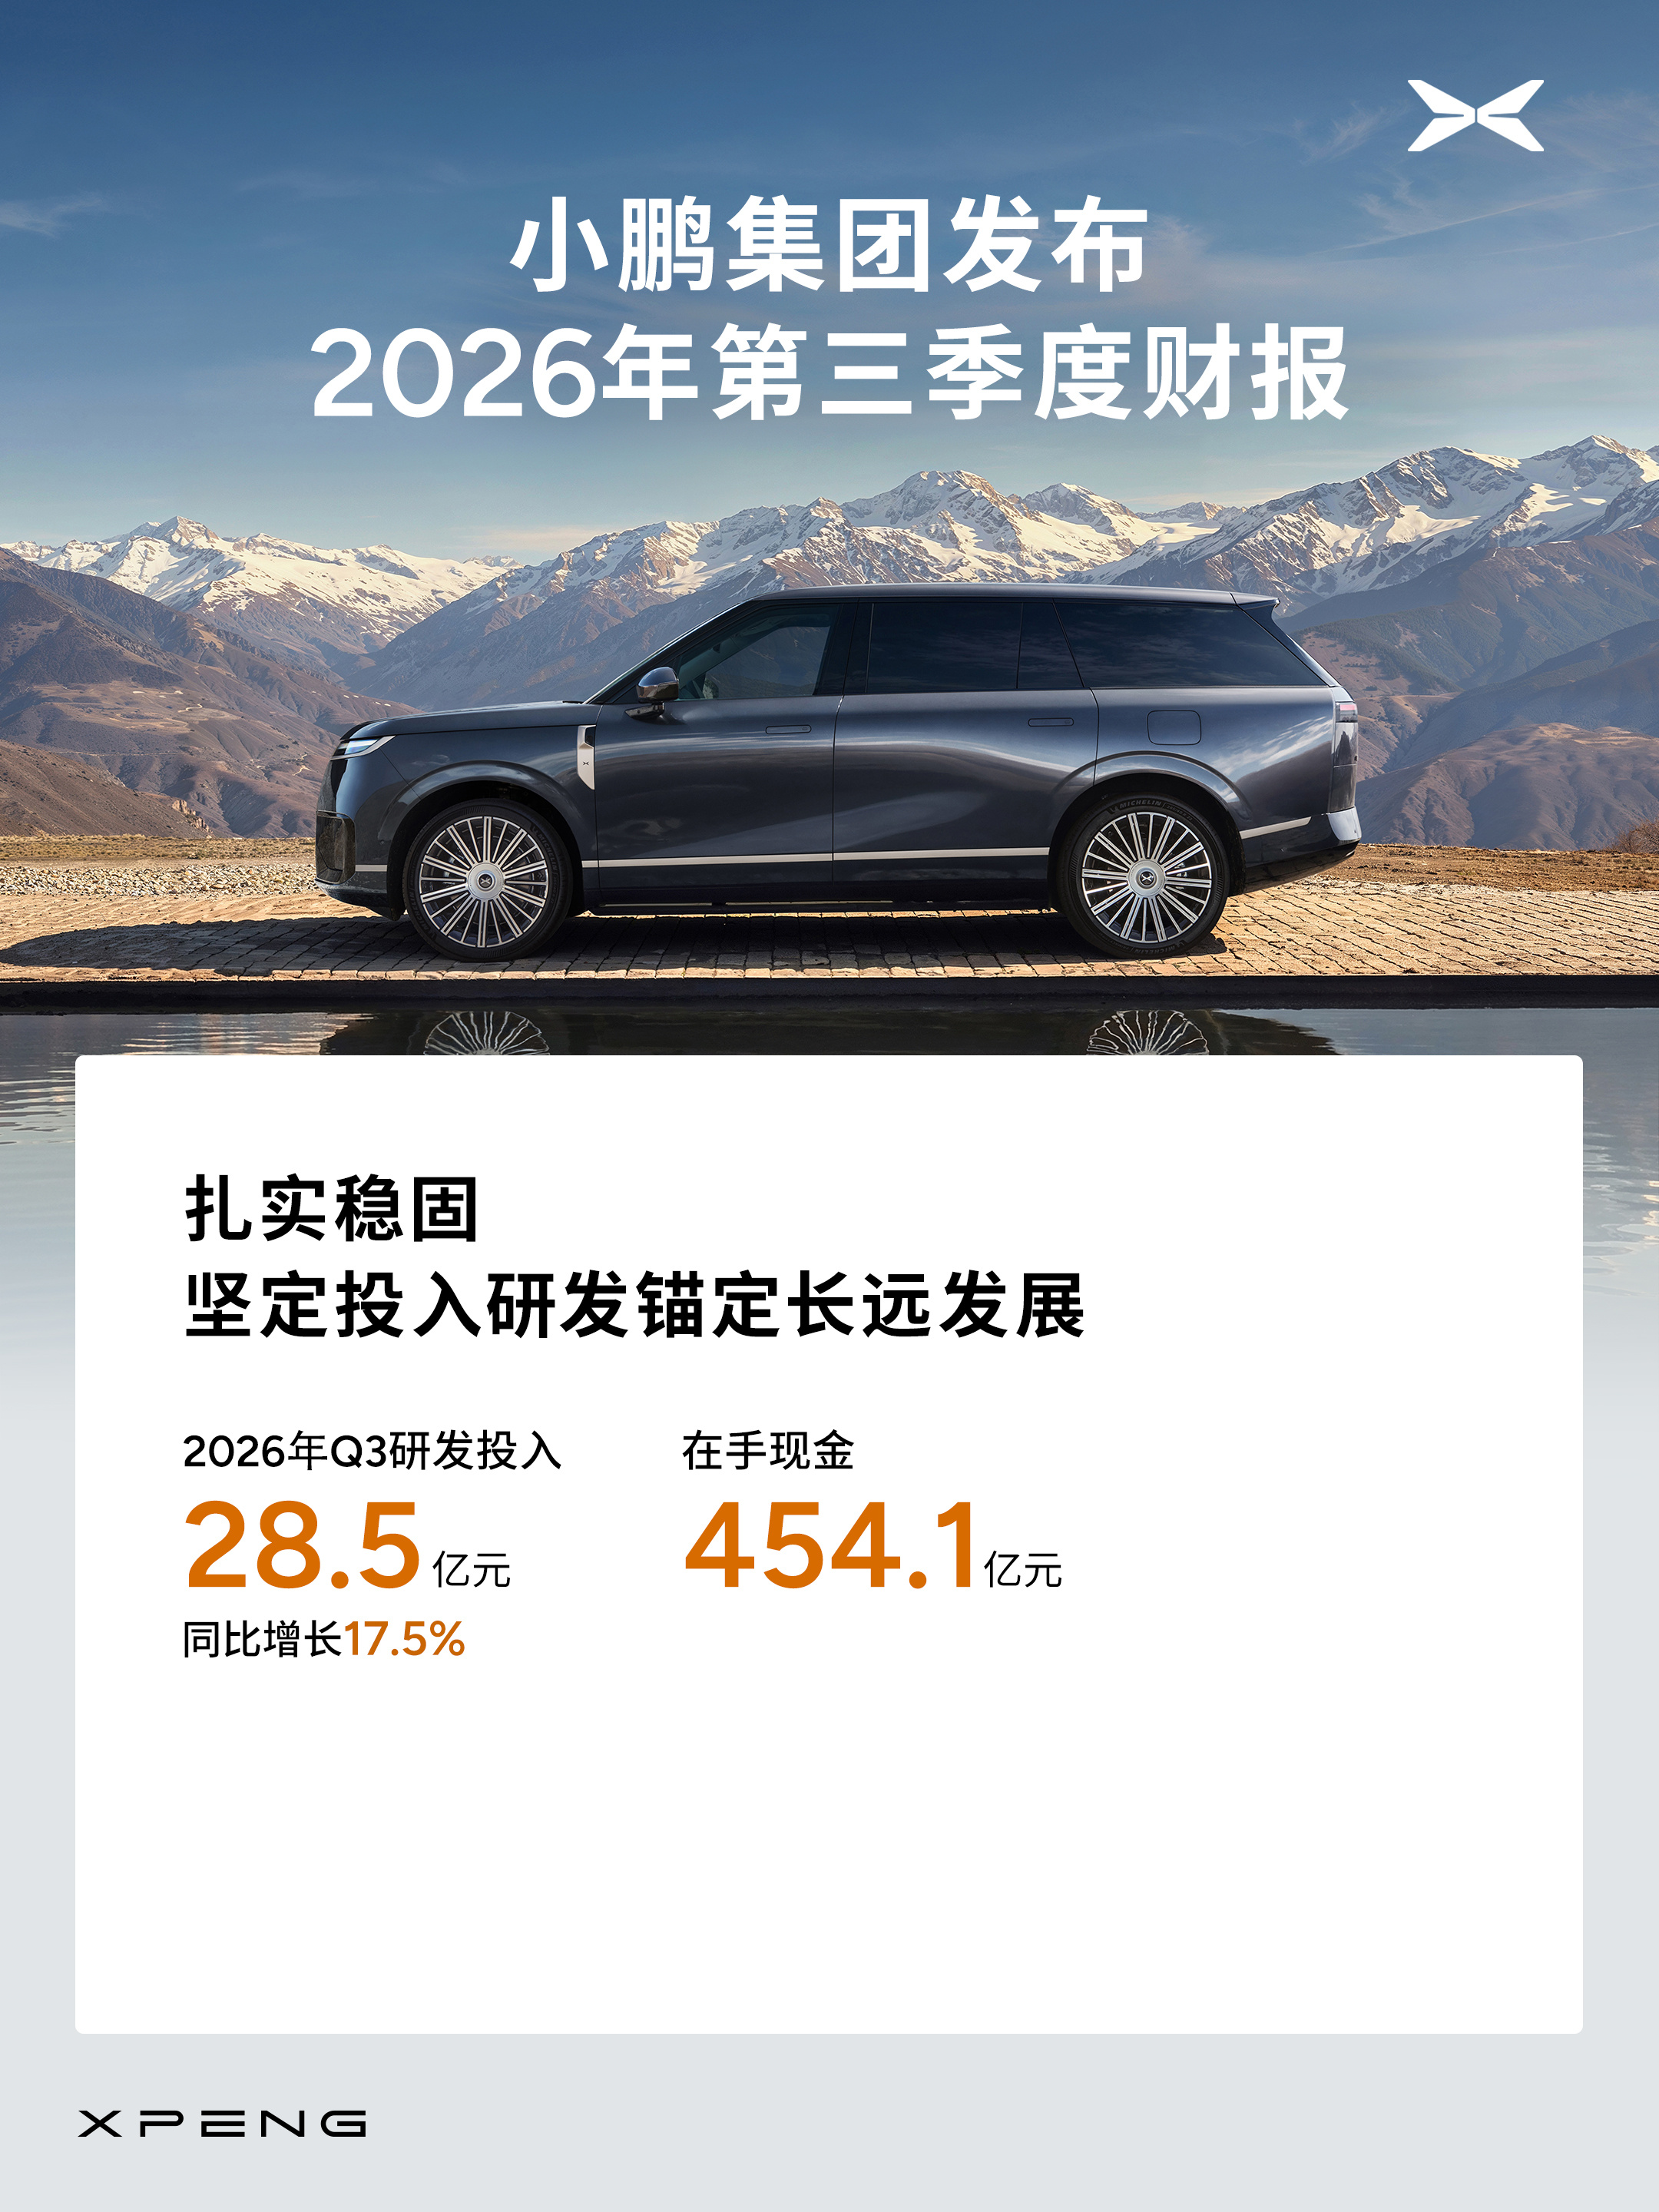 Photo: 小鹏汽车 on Weibo — original post
Enjoyed this? Get the next one direct.
New articles, or a daily / weekly digest — delivered to your inbox.